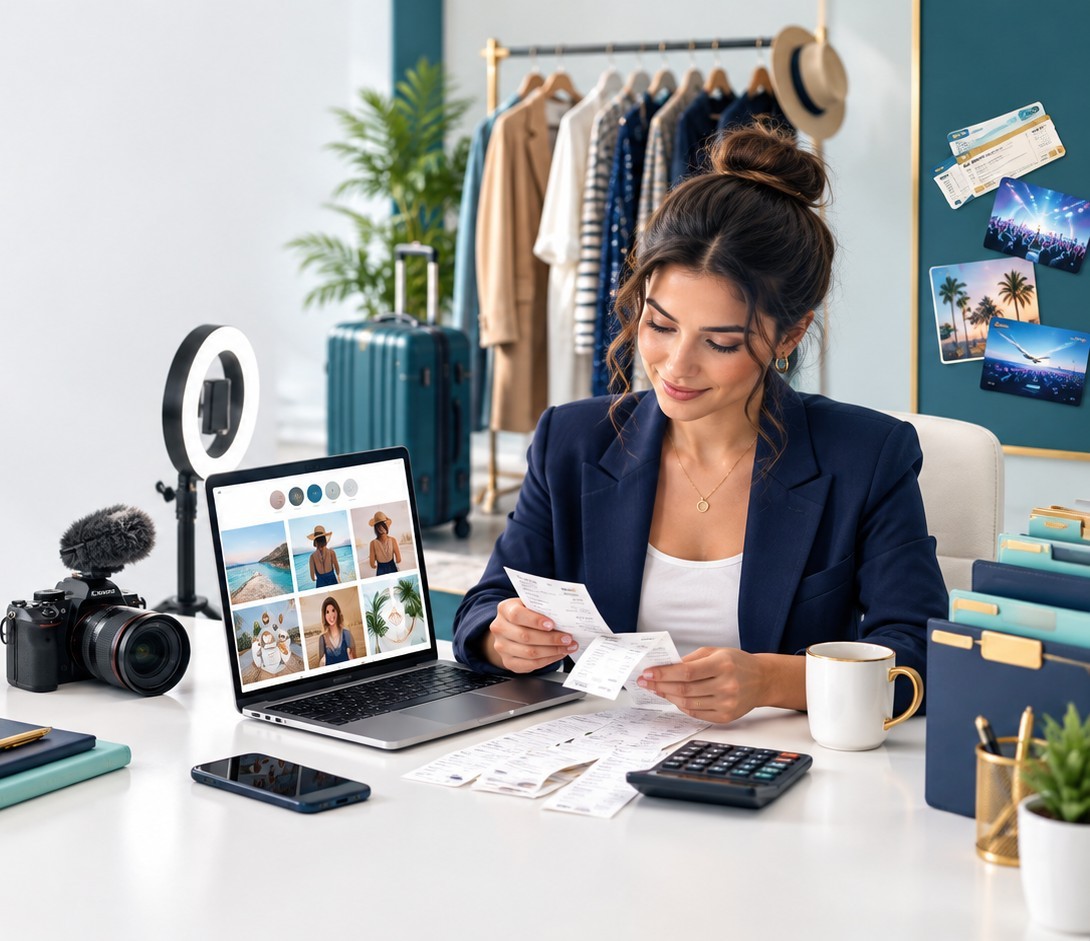
Social-media influencing can be a legitimate business. Income may come from brand partnerships, affiliate links, platform payments, merchandise sales, appearances, subscriptions, consulting, or advertising revenue. But having followers—or simply posting photos and videos—does not automatically turn personal spending into deductible business spending. The tax authorities might consider it as a hobby and disallow those related expenses.
Profit Purpose Comes First
For influencers, the most important tax issue is the profit purpose. A creator must be operating with a real, bona fide objective of earning a profit, rather than engaging in a personal hobby that happens to produce occasional income. This is especially important for newer creators who have limited revenue, recurring losses, or content centered on their personal lifestyles.
A profit-oriented influencer business should look and operate like a business. Helpful evidence includes:
- A monetization plan identifying revenue sources, such as sponsorships, affiliate commissions, merchandise, appearances, or platform revenue.
- Regular outreach to sponsors, brands, agencies, or potential clients.
- Separate business banking and organized accounting records.
- Written contracts, campaign briefs, pricing, and defined deliverables.
- A content calendar and regular business activity.
- Documented efforts to improve profitability when results are limited.
An influencer should be able to explain how the activity is expected to produce income—not merely how it is expected to grow followers or views.
Business Expenses Must Be Ordinary, Necessary, and Documented
Once the profit purpose is established, each expense must still meet the usual business-deduction standards. Generally, an expense must be ordinary and necessary for the business, primarily business rather than personal, and supported by records.
The fact that an item appears in a TikTok, Instagram, YouTube video, or other post may help establish a business connection. However, it does not, by itself, make the expense deductible.
Clearly business-related costs may include cameras, lighting, editing software, dedicated website hosting, payments to editors or photographers, booking-agent commissions, paid advertising, platform fees, and payment-processing fees. Influencers should retain invoices, proof of payment, contracts, a brief explanation of business purpose, and copies or links to the resulting work product.
Mixed-Use Expenses Require an Allocation
Some expenses have both personal and business use. These may include cell phones, internet service, vehicles, home-office space, computers, travel, and equipment.
Only the business portion is generally deductible. The creator should use a reasonable allocation method and retain support for the percentage claimed. Useful records include mileage logs, usage records, receipts, content schedules, calendars, and contemporaneous notes describing the business purpose.
For example, a creator who uses a vehicle to travel to a sponsored photo shoot may deduct the documented business mileage. The same vehicle’s personal commuting, errands, and family travel remain personal expenses.
Lifestyle Expenses Receive Extra Scrutiny
The highest-risk expenses are those that are inherently personal, including clothing, grooming, meals, vacations, entertainment, luxury purchases, celebrity or athlete experiences, and family travel.
These costs demand unusually strong documentation. A defensible file may include a written campaign brief, sponsor requirements, a contract, defined deliverables, dated content, proof of payment, and evidence connecting the expense to revenue-producing activity.
The key question is not simply whether the creator posted about the experience. The question is whether the cost was incurred primarily for business rather than personal enjoyment. A paid campaign requiring a creator to attend a particular event and produce specified content presents a much stronger deduction than a personal vacation that later appears in a social-media post.
Three Relevant Tax Court Cases
Sami v. Commissioner, T.C. Memo. 2026-69
In Sami v. Commissioner, the Tax Court considered claimed influencer-related marketing expenses involving celebrity events, meet-and-greets, athlete experiences, and similar expenditures. The court disallowed approximately $97,505 of claimed advertising expenses because the taxpayer did not establish that they were primarily business expenses rather than personal ones.
The decision is a strong reminder that content creation, potential follower growth, and possible promotional value do not alone establish a deduction. The taxpayer must prove that the expense was primarily undertaken for business, was ordinary and necessary, and was adequately
Tucker v. Commissioner, T.C. Memo. 2023-87
In Tucker v. Commissioner, the court allowed only deductions and cost-of-goods-sold items supported by credible evidence. The case is particularly relevant to fashion, lifestyle, and merchandise-focused creators because it reinforces the importance of invoices, inventory records, payment documentation, and proper timing of deductions.
Gayle Gaston v. Commissioner, T.C. Memo. 2021-107
In Gayle Gaston v. Commissioner, the court emphasized the threshold issue of profit motive. For influencers with low or inconsistent income, the case highlights why businesslike operations, records, monetization efforts, and efforts to improve profitability are essential.
The Practical Takeaway
Influencers should treat their activity as a real business from the beginning. Maintain a clear profit strategy, separate business and personal finances, preserve contemporaneous documentation, and be conservative with personal or lifestyle expenses.
The more personal an expense appears, the stronger the evidence must be that it was incurred primarily to produce income.
