Philadelphia’s Proposed BIRT Exemption: Small-Business Relief With Two Big Questions
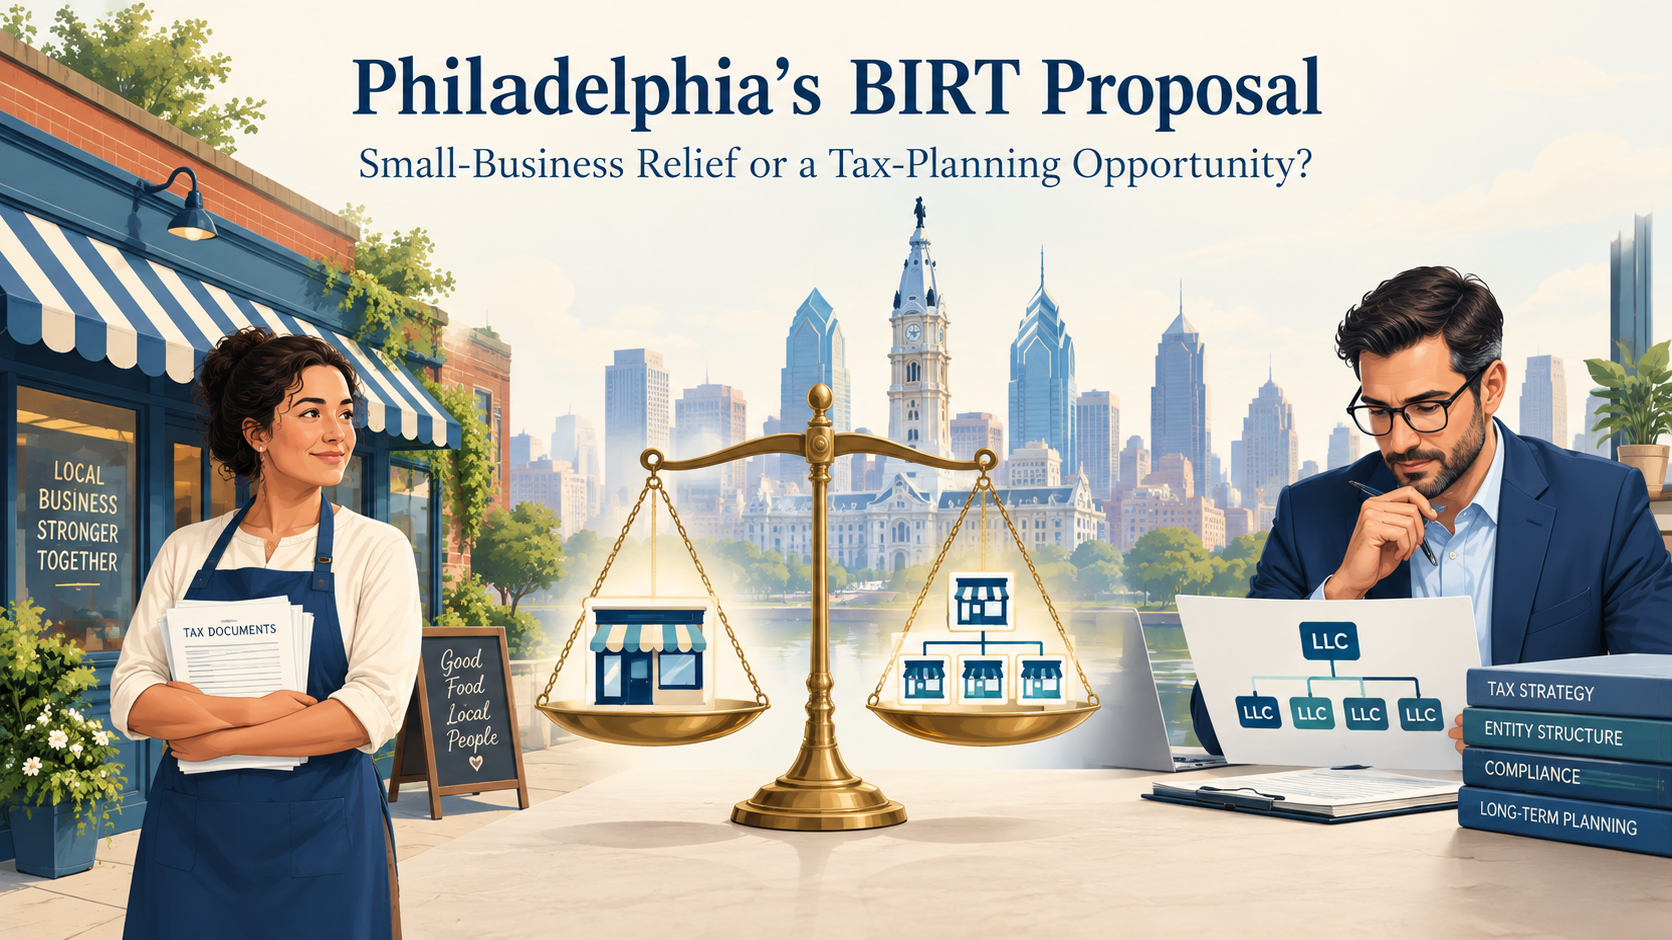
Philadelphia’s small businesses need meaningful tax relief. But a proposal to exempt sole proprietors and single-member LLCs from the Business Income and Receipts Tax, commonly known as BIRT, raises two important questions: Would the exemption withstand a PA constitutional challenge? And could it create tax-saving opportunities for larger, more profitable businesses?
An October 8, 2026, Philadelphia Inquirer article reports that Councilmember Mike Driscoll’s proposal remains stalled in City Council’s Finance Committee. According to Driscoll, Council President Kenyatta Johnson has been reluctant to advance legislation that could reduce City revenue. The proposal would exempt sole proprietors and single-member LLCs from BIRT, providing relief to many businesses affected by the elimination of the City’s $100,000 BIRT exclusion.
A Small-Business Initiative Worth Recognizing
I first became familiar with this initiative in January 2025, when I saw early presentation materials involving Jigar Mehta and the Asian American Chamber of Commerce. I also spoke with Mr. Mehta and was struck by how personally and passionately he approached the issue.
His persistence deserves recognition. Advocating for small businesses takes time, patience, and a willingness to keep pushing when progress stalls. The Inquirer identifies Mehta as a champion of the idea behind Driscoll’s legislation.
The goal is understandable. Eliminating the $100,000 BIRT exclusion brought many small businesses back into the tax’s filing and payment requirements. But supporting relief does not mean overlooking questions about how that relief would work—or who would ultimately benefit.
- Would the Exemption Resolve the Uniformity Issue—or Create Another One?
The constitutional question is central because it helped drive the elimination of the previous tax break.
According to the Inquirer, Philadelphia’s Law Department concluded that Pennsylvania courts would likely find the $100,000 exclusion inconsistent with the state Constitution’s uniformity clause, which is was also shared in the Philadelphia Tax Reform Commission. The concern was that the exclusion produced different effective tax rates depending on the business’s size based on revenues. That was the City’s legal assessment, however—not a court ruling declaring the Philadelphia exclusion unconstitutional. Some tax attorneys disagreed with the administration’s position, but at the end, the Mayor Parker took a final decision.
The new proposal takes a different approach: instead of excluding a dollar amount from taxation, it would exempt entire categories of businesses—sole proprietors and single-member LLCs. Supporters intend that distinction to provide a legally defensible alternative.
But consider two otherwise comparable businesses:
- One LLC has a single individual owner holding 100% of the ownership interests.
- Another LLC has two individual owners, with one holding 99.9% and the other holding 0.1%.
Based on the proposal described in the Inquirer, the first could qualify for the BIRT exemption, while the second would remain subject to BIRT—even if both businesses had the same revenue, profit, and business activities.
That raises an important policy question: Should adding a second owner, even one with a very small interest, materially change a business’s Philadelphia tax burden?
It also raises a legal question: Is this ownership-based distinction a permissible classification for purposes of Pennsylvania’s uniformity requirement?
The fact that a proposal treats businesses differently does not, by itself, establish that it is unconstitutional. For example, currently corporations are subject to only Birt while other entities like partnerships and sole owners are subject to Birt and NPT. The bill’s exact language and the legal justification for its classifications would matter. Nevertheless, this issue deserves a clear explanation before the legislation moves forward.
BIRT and NPT Must Be Considered Together
The analysis also needs to account for Philadelphia’s Net Profits Tax, or NPT.
The City explains that NPT applies to unincorporated businesses and does not replace the net-income portion of BIRT. To reduce overlapping taxation, eligible taxpayers may claim an NPT credit based on 60% of the BIRT net-income tax. The gross-receipts portion of BIRT is not included in that credit.
As a result, exempting a business from BIRT would not necessarily eliminate its Philadelphia business-tax liability. Its NPT liability could remain, without the credit associated with paying part of the BIRT.
The practical question is therefore broader than “Who stops paying BIRT?” It is “How would the combined BIRT and NPT burden change for different ownership structures?”
- Could the Exemption Benefit Larger Businesses Through Restructuring?
The second concern is whether a measure intended to help small businesses could also provide substantial savings to larger businesses.
The Inquirer reports that the Department of Revenue has already identified this risk. In its fiscal analysis, the administration warned that businesses might change their structures specifically to qualify for the exemption, increasing potential revenue losses. The article cites real estate investors as one example of taxpayers who could benefit.
A simplified professional-services example helps illustrate the incentive.
An Illustrative Example: A Four-Partner Law Firm
Assume a law firm operates as a partnership with:
- $30 million in annual revenue.
- $4 million in taxable net profit.
- Four equal partners who are Philadelphia residents.
- All revenue and profit attributable to Philadelphia.
For consistency with the original example, the calculations below use tax year 2025 rates: 5.71% for BIRT net income, 0.141% for BIRT gross receipts, and 3.74% for resident NPT.
Under the existing structure, the calculation would be:
| Tax component | Calculation | Amount |
| BIRT—net income | $4,000,000 × 5.71% | $228,400 |
| BIRT—gross receipts | $30,000,000 × 0.141% | $42,300 |
| Total BIRT | Net-income tax plus gross-receipts tax | $270,700 |
| NPT before credit | $4,000,000 × 3.74% | $149,600 |
| NPT credit | $228,400 × 60% | ($137,040) |
| NPT after credit | $149,600 − $137,040 | $12,560 |
| Combined BIRT and NPT | $270,700 + $12,560 | $283,260 |
A Hypothetical Alternative Structure
Now suppose each partner owns a separate single-member LLC, and the partnership pays each LLC $1 million for services.
For purposes of illustrating the policy concern, assume:
- The payments are respected as deductible expenses that reduce the partnership’s taxable net profit to zero.
- Each LLC reports $1 million in taxable net profit.
- Each LLC qualifies for the proposed BIRT exemption.
- The LLC income remains subject to resident NPT.
- No other taxes, adjustments, or restrictions change the result.
Under those assumptions:
| Tax component | Calculation | Amount |
| Partnership BIRT—net income | $0 × 5.71% | $0 |
| Partnership BIRT—gross receipts | $30,000,000 × 0.141% | $42,300 |
| Partnership NPT | No taxable net profit | $0 |
| Four LLCs—combined BIRT | Assumed exempt under the proposal | $0 |
| Four LLCs—combined NPT | $4,000,000 × 3.74% | $149,600 |
| Combined BIRT and NPT | $42,300 + $149,600 | $191,900 |
The difference would be $91,360 annually—approximately 2.28% of the firm’s $4 million in profit.
An Incentive Illustration, Not a Ready-Made Tax Strategy
This example does not establish that a law firm could achieve that result simply by forming four LLCs and redirecting payments.
It assumes that the payments, deductions, income allocations, and exemption eligibility would all be respected. Those are issues that would require separate analysis under the enacted legislation and applicable tax rules.
The point is narrower: an exemption based on ownership structure rather than business size could create a meaningful financial incentive to reorganize. A business with $30 million in revenue might benefit, while a much smaller business with two owners could remain subject to BIRT.
That is the unintended consequence policymakers should address.
What Should Be Clarified Before the Proposal Advances?
Before adopting the exemption, the City should clearly address:
- The legal basis for distinguishing single-owner businesses from otherwise comparable multiple-owner businesses.
- The precise eligibility rules, including how the exemption would apply to LLCs with entity owners or different tax classifications.
- Whether related-party payments or restructuring could shift income into exempt businesses.
- The combined BIRT and NPT effect—not just the reduction in BIRT.
- Whether projected revenue losses adequately account for businesses changing their structures.
The administration estimated that the proposal would cost approximately $29.5 million annually, while also warning that restructuring could increase that amount. Understanding the assumptions behind that estimate is an important part of evaluating the bill.
Our Perspective
We support efforts to make Philadelphia’s tax system more manageable for small businesses, and we commend the persistence of those working toward that goal.
But the details matter. Relief should rest on a sound legal foundation and avoid creating unnecessary disparities between similar businesses—or incentives that extend the benefits far beyond the intended audience.
We will continue monitoring the proposal, with particular attention to its constitutional justification, eligibility requirements, and potential restructuring consequences.
Article Philadelphia Inquirer – Council President Kenyatta Johnson is holding up a bill aimed at providing tax relief for Philly’s small businesses
