ira

Traditional or Roth? A Fresh Look at Your 2026 Retirement Contributions

Retirement Contributions for 2026: Plan Now, Avoid a Year-End Scramble As year-end approaches, retirement contributions deserve a place on your tax-planning checklist. Whether you contribute through an employer’s 401(k), fund an IRA, or maintain a retirement plan for your business, reviewing your options now can help you avoid missed deadlines and identify potential tax savings.
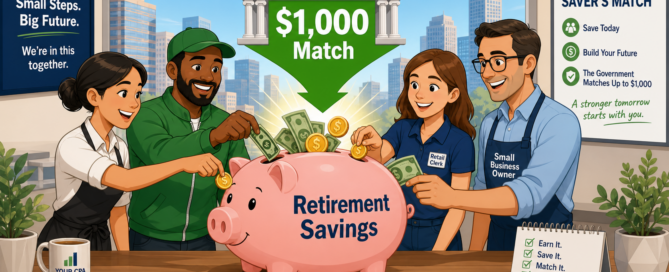
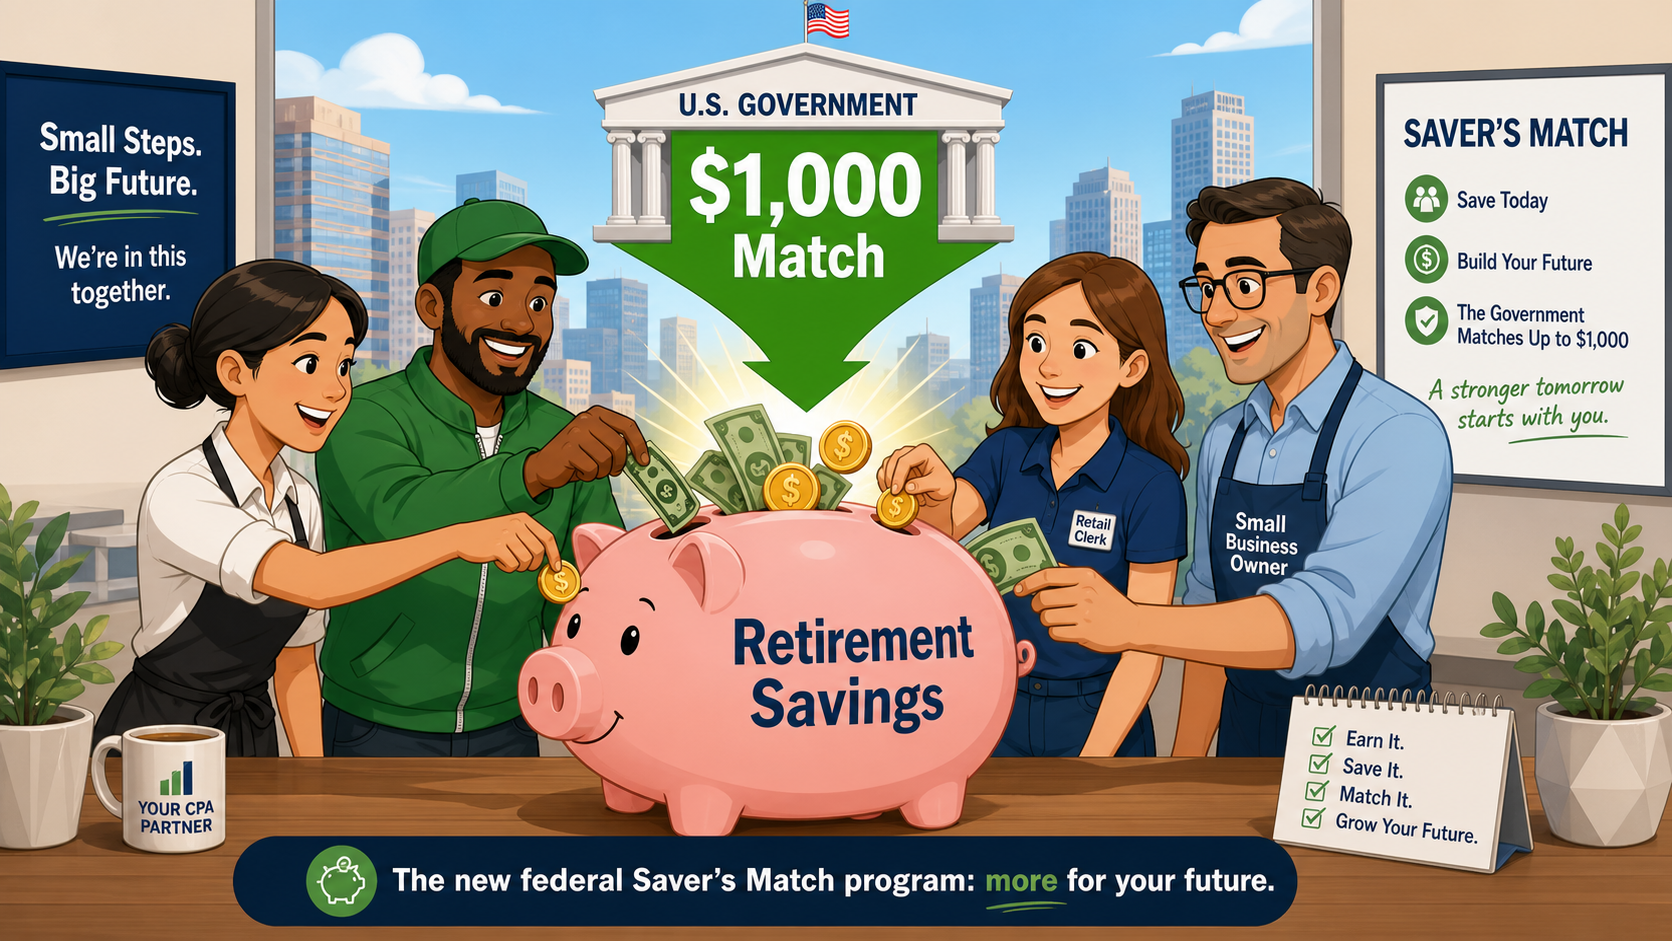
How the New Saver’s Match Can Turn $2,000 of Savings Into $3,000 for Your Retirement

From 2027, taxpayers will have access to a powerful new retirement tool: a federal matching contribution of up to $1,000 per year for eligible savers, if their employer (or themselves if self-employed) does not offer a 401(k) or similar plan (note that plenty of States have requirements for employers). This new option builds on the “Saver’s Match”

By |2026-05-14T17:04:41+00:00June 15th, 2026|Categories: Business, Individuals|Tags: , , , , , , , |

Don’t Get Penalized This Holiday Season: Make Your RMD on Time

As the year wraps up and everyone’s busy before New Year’s Eve, the IRS has one more reminder for those with retirement accounts: Required Minimum Distributions (RMDs). If you’re age 73 or older (or turning 73 this year), most tax-deferred retirement accounts — traditional IRAs, 401(k)s, 403(b)s, etc. — require you to take a minimum

By |2025-12-04T05:11:20+00:00December 27th, 2025|Categories: Individuals|Tags: , , , , , , , , , |

Avoid Tax Pitfalls and Maximize Gains: 4 Key Investment Tactics

There are many tax strategies that are overlooked levers for improving investment outcomes. Reviewing a client’s tax return isn't just a compliance exercise—it’s an opportunity to identify meaningful, actionable ways to reduce tax drag and improve long-term financial outcomes. When integrated with a thoughtful investment plan, tax planning becomes a powerful tool to grow and

Retirement options for a non working spouse

In many couples, there is one spouse that might not be working at a w2 job or being self-employed. The "non working" spouse is usually managing the household ensuring it runs smoothly, which can be a 24/7 job especially if there are children. In many of these cases, the "non working" spouse is supporting cost-saving

By |2025-01-11T19:15:13+00:00March 24th, 2025|Categories: Individuals|Tags: , , , , , , , , , , , |

Putting your kids on payroll for tax savings

If you are a business owner, it might be positive to employ your kids or other family members in the business. Especially, if you are already supporting these individuals at your higher tax rate, it might be quite beneficial to have an expense for the business and save on the taxes paid a lower rate

By |2024-12-15T05:34:03+00:00March 3rd, 2025|Categories: Business, Individuals|Tags: , , , , , , , , , , |

Should you consider a Backdoor Roth contribution?

Brief History First let’s start with a brief history on the Roth IRAs and how paying taxes today might* avoid them at retirement time (distribution). The word might* in the previous sentence is because we never know if Roth IRA will be taxed in the future (i.e. Social Security benefits began to be taxed in

By |2024-12-15T04:28:25+00:00February 17th, 2025|Categories: Business, Individuals|Tags: , , , , , , |

One in five Americans has no retirement savings – what are my options?

With the increase cost of living (inflation) and other factors, one in five Americans has no retirement savings and over half of them consider that they have not enough for retirement. Based on our experience, we consider that the vast majority of Americans is not ready for retirement as a) cost of healthcare and homecare

By |2024-12-02T03:12:09+00:00February 10th, 2025|Categories: Business, Individuals|Tags: , , , , , , , |

IRS announces 2022 retirement changes

In the Tax Tip 2021-170 communication, the IRS announced that the 2022 contribution limit for 401(k) plans will increase to $20,500. Traditional IRA income phase-out ranges for 2022 are: $68,000 to $78,000 - Single taxpayers covered by a workplace retirement plan $109,000 to $129,000 - Married couples filing jointly. This applies when the spouse making

By |2025-01-09T12:44:26+00:00November 17th, 2021|Categories: Individuals|Tags: , , , , , , , , |
Go to Top