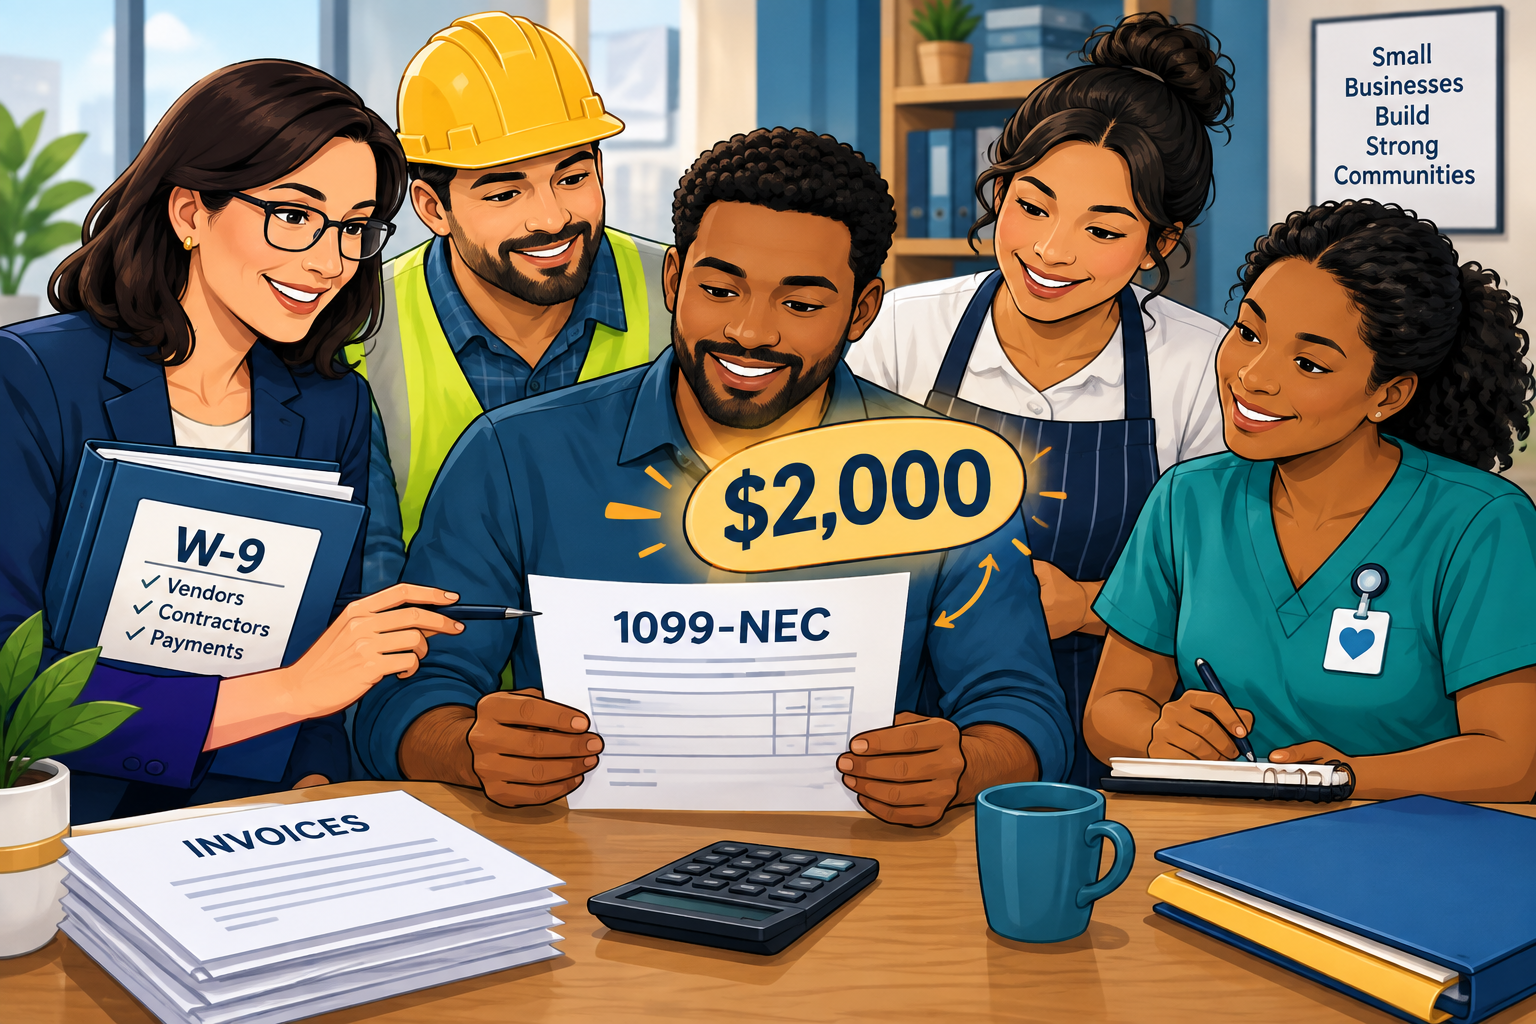
Small-business owners who pay independent contractors have an important administrative change to keep in mind for 2026: the federal reporting threshold for many Forms 1099-NEC increased from $600 to $2,000. That may reduce the number of forms some businesses file next January, but it does not eliminate the need for good vendor records, completed W-9 forms, certificate of insurance (to avoid paying workers compensation twice) or accurate bookkeeping.
For construction companies, professional services, healthcare & personal wellness, transportation, real estate, cleaning businesses, and other service-based companies, this is a good time to review contractor payments before the year-end filing rush begins.
What changed
For payments made during calendar year 2026, a business generally must file Form 1099-NEC when it pays $2,000 or more to a nonemployee for services performed in the course of the business. The threshold was $600 for payments made before 2026, and the $2,000 amount may be adjusted for inflation beginning in 2027.
Form 1099-NEC is commonly used for payments to qualifying independent contractors, consultants, repair vendors, subcontractors, freelance professionals, and certain attorneys. The form reports nonemployee compensation; it is not a payroll form and does not determine whether someone is properly classified as an employee or contractor.
What the new threshold does not change
The new $2,000 threshold is helpful, but business owners should not treat it as a reason to stop collecting vendor information.
A few important reminders:
- A payment below $2,000 may not require a Form 1099-NEC, but it is still a business expense that should be properly recorded in the books.
- A contractor’s income remains taxable even if no Form 1099 is issued.
- A completed Form W-9 is still the best starting point when engaging a new vendor or contractor. It provides the legal name, business name, address, tax classification, and taxpayer identification number needed to prepare an information return if one becomes required.
- If you do not want unpleasant surprises in the annual workers’ compensation audit, make sure you obtain the certificate of insurance
- The $2,000 threshold does not replace the need to consider whether a worker should be treated as an employee. That question depends on the actual working relationship, not simply on the dollar amount paid or the existence of a contractor agreement.
Watch how payments are made
How a business pays a vendor can affect who handles information reporting.
Generally, when a business pays a contractor by check, ACH, cash, wire, or similar direct method, the business should track those payments for potential Form 1099-NEC reporting. When a business pays through a credit card or a third-party payment network, such as certain online payment platforms, the payment settlement entity may handle reporting on Form 1099-K instead. Businesses should still keep complete expense records, even where they do not expect to issue a Form 1099-NEC themselves.irs+1
Form 1099-K rules are separate. For third-party network transactions, the federal reporting threshold generally applies when gross payments exceed $20,000 and the number of transactions exceeds 200; payment-card transactions are subject to separate reporting rules.irs+1
Closing thought
The increase to $2,000 may mean fewer Form 1099-NEC filings for some small businesses, but it does not make contractor recordkeeping less important. Collecting Forms W-9 early, recording payments consistently, and understanding how vendors are paid can help prevent avoidable issues when January filing deadlines arrive. When there is uncertainty about a payment or a worker relationship, it is far easier to address it before year-end than during the annual 1099 filing rush.
