IRS nonfiler cases: Delays and renewed enforcement
A recent Treasury Inspector General for Tax Administration (TIGTA) review highlights a significant issue in the IRS’s efforts to pursue high-income taxpayers who have not filed required federal tax returns. The findings also reinforce an important practical point: a delayed IRS notice should never be mistaken for a resolved tax obligation.
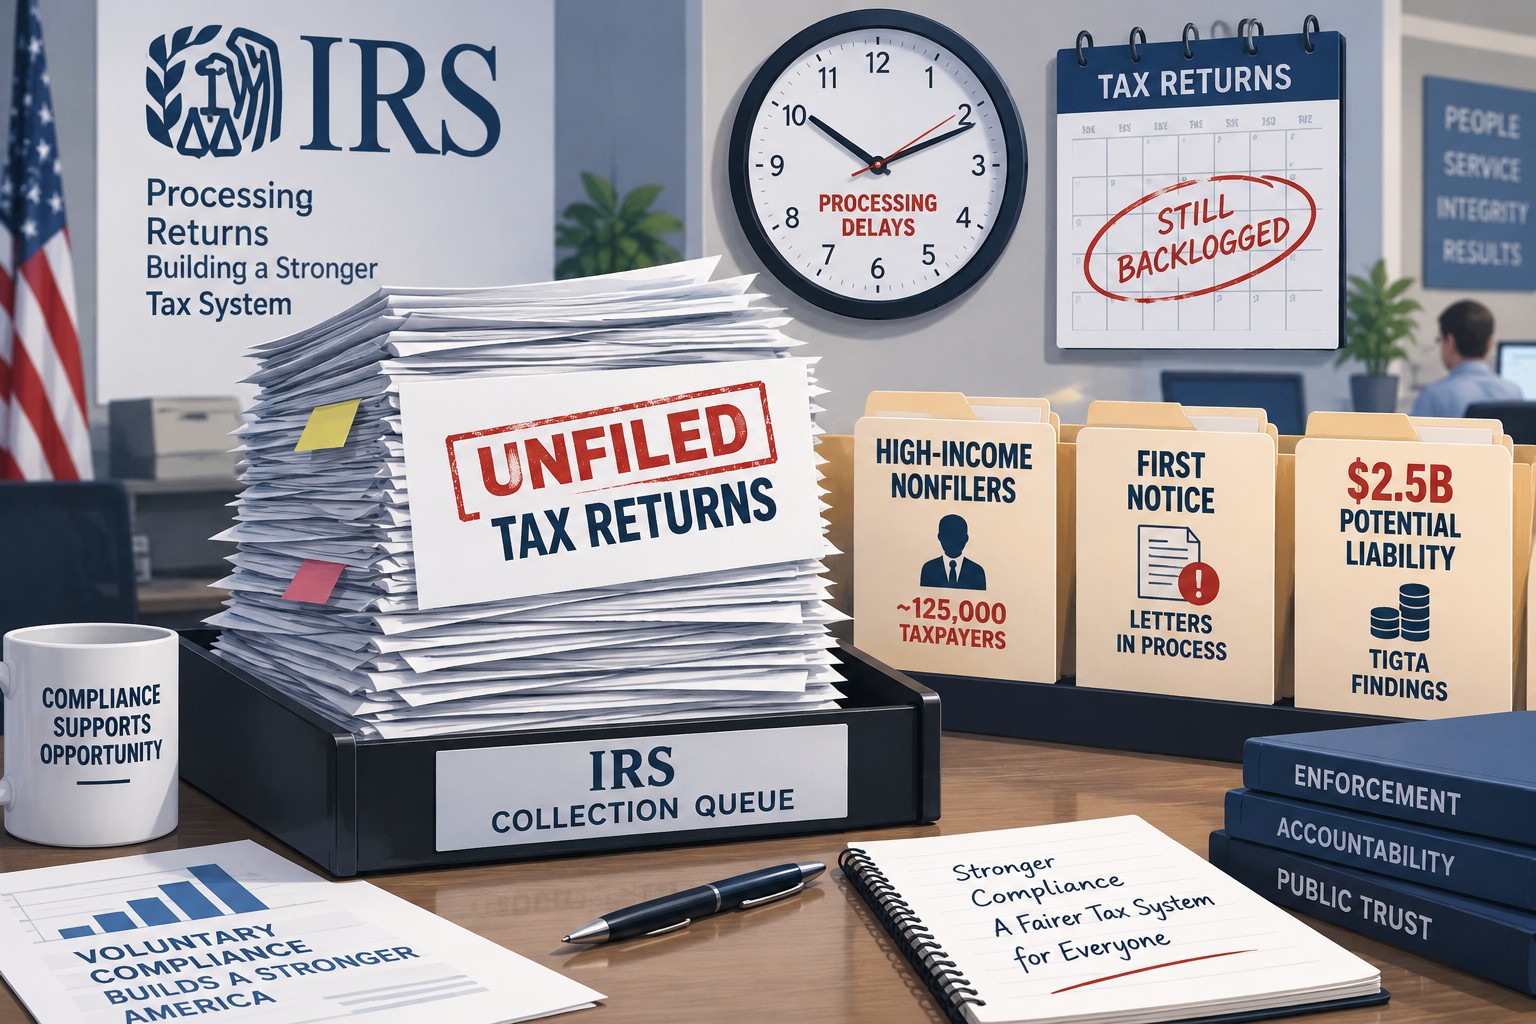
TIGTA reviewed the IRS’s high-income nonfiler initiative, which began in February 2024 and included taxpayers with income of $400,000 or more, as well as certain federal and IRS employees and taxpayers identified through a Senate Finance Committee request. After excluding cases that did not receive notices or had other distinguishing factors, TIGTA analyzed 111,566 cases. As of June 30, 2025, 81,417 cases—or 73%—still had no return filed and no assessment made.
Thousands stalled after first notice
The review found that 38,824 high-priority cases involving 33,653 taxpayers remained in “first-notice” status. Under normal IRS procedures, a taxpayer who does not file after receiving an initial notice would generally receive a final notice approximately eight weeks later. Instead, these cases did not move forward through the usual return-delinquency process.
According to TIGTA, IRS collection management requested that final notices be delayed in March 2024 because of concerns about having enough resources to work the cases. The delay prevented additional collection notices and enforcement actions. TIGTA later identified that the cases were stalled because of a systemic error, and the IRS reported that it advanced nearly 39,000 affected cases in March 2026.
Those stalled cases represented roughly $15.7 billion in potential tax assessments. TIGTA estimated that earlier action could have produced returns or assessments in 10,482 cases and approximately $321.3 million in additional tax.
More cases await assignment
TIGTA also identified 10,969 high-priority cases involving 8,853 taxpayers that were waiting in the IRS collection queue for assignment as of June 30, 2025. Together, those cases represented approximately $2.5 billion in potential tax liability.
The watchdog estimated that prioritizing the queued inventory could result in returns or assessments in 2,962 cases involving 2,399 taxpayers, producing approximately $90.8 million in additional tax due. By December 31, 2025, the IRS had reduced the number of queued cases to 9,463.
What taxpayers should take away
The report does not mean every recipient of an IRS nonfiler notice has failed to file. TIGTA found that the IRS issued initial notices in 4,918 cases involving taxpayers who had already filed returns; in many instances, the returns had not yet been processed and posted to IRS accounts. Some of those returns took more than one year to post.
Still, taxpayers who have not filed one or more returns should not assume that the IRS has lost interest simply because notices have been delayed. Enforcement activity may resume later, and unfiled returns can lead to substitute-for-return assessments, penalties, interest, liens, levies, and increasingly complex resolution options.
If you receive a nonfiler notice but believe you already filed, confirm that the IRS has processed and posted the return. If returns are actually outstanding, addressing the issue promptly—before enforcement escalates—is usually the most effective and least costly path forward.
Journal of Accountancy – IRS delayed action on thousands of high-income nonfiler cases, TIGTA says
